

OneMain Financial

- 3.33K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on OneMain Financial from Appgk
Managing a loan is rarely something I want to do when I have plenty of time and perfect concentration. More often, I am checking a due date between errands, confirming whether a payment went through, or trying to understand my credit picture on a small phone screen. That is the context in which I looked at OneMain Financial, a free finance app from OneMain Financial for people who already use the company’s loan services.
The app is built around a narrow but useful purpose: handling loan-related tasks without relying entirely on a browser or a phone call. Its store summary focuses on managing a loan, making payments, and tracking credit, and that description matches the way I approached it. I did not see it as a complete personal-finance dashboard or a replacement for a bank app. I saw it as a focused companion for keeping one particular financial relationship easier to monitor.
That focus is both its strongest quality and its main limitation. If your goal is to stay on top of a OneMain loan, the app can reduce small bits of friction. If you want detailed budgeting, investment tracking, bill negotiation, or a broad view of accounts from different providers, you will probably need another tool alongside it.
How clearly the app presents everyday loan tasks
Readability and navigation for routine checks
My first impression was that the app’s value depends less on discovering hidden tools and more on finding the few actions most borrowers need quickly. A loan app should make the current situation understandable at a glance: what needs attention, whether a payment is pending or completed, and where to go when I want to review credit information. OneMain Financial is at its best when I treat it as a repeat-use utility rather than an app I explore for entertainment.
Best Parts of OneMain Financial
Things to Keep in Mind About OneMain Financial
The interface is easier to approach when I have a specific question in mind. For example, I might open it to check the next payment before payday, confirm that I used the correct payment method, or review a recent account change. This task-first approach is helpful for people who find large finance dashboards overwhelming. Instead of asking me to build a complete financial picture, the app keeps the loan relationship at the center.
That simplicity can also make the experience feel limited. Someone accustomed to a banking app that combines checking, savings, cards, transfers, spending categories, and alerts may find the narrower navigation less satisfying. The app is not designed to become the single place for every financial decision. I would keep my main banking app available for cash-flow planning and use this one for the OneMain-specific details.
News and Features Related to OneMain Financial

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
For readability, I found it sensible to avoid rushing through screens that involve payment amounts or account information. Financial apps reward careful reading, especially when a screen contains several dates or choices that look similar. My practical tip is to open the app when you are not already distracted, review the amount and timing before confirming anything, and keep the confirmation screen available until you are sure the action has completed.
The credit area deserves a different reading style from the loan area. A credit view can be useful for spotting changes in your broader financial position, but it should not be treated as a complete explanation of why a score or report changed. I would use it as a regular checkpoint, then investigate important changes through the relevant credit-reporting or financial source before making a major decision.
Don't want to read the full review?
What the app is like for different reading needs
People with low vision, reading fatigue, or attention difficulties may appreciate the app’s focused purpose, because there are fewer categories to learn than in a full-service money manager. The most useful habit is to slow the process down and verify labels rather than relying only on color, position, or a quick glance. A payment screen is not the place to guess which control is active.
At the same time, a focused finance app is not automatically accessible to everyone. Text size, contrast, screen-reader behavior, and the clarity of error messages can vary with the phone, operating system, and current app version. I would not assume that a person who needs enlarged text, spoken feedback, or simplified interaction will have the same experience I did. The sensible approach is to test the key journey first: sign in, locate the loan, read the amount due, and reach the payment confirmation without assistance.
Screenshots
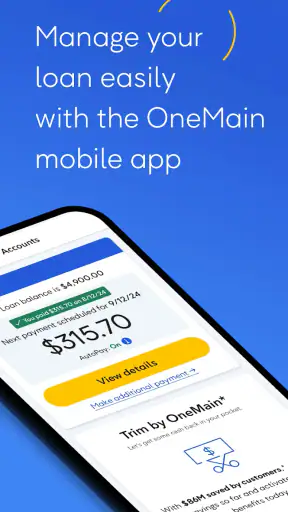
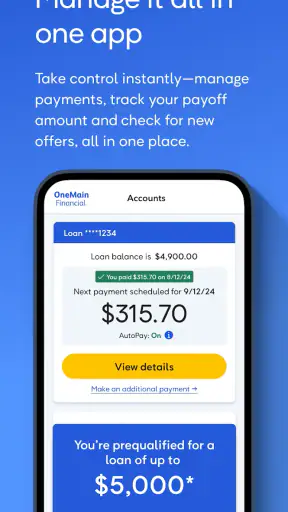
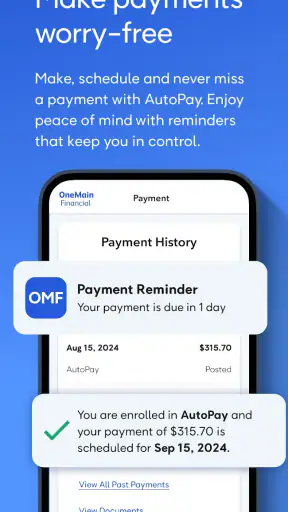
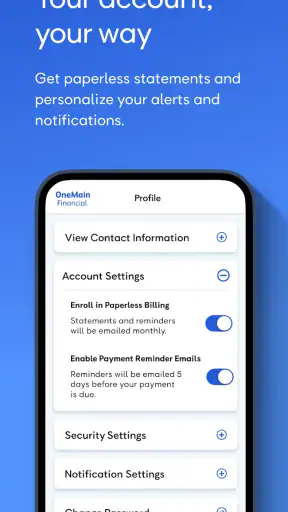
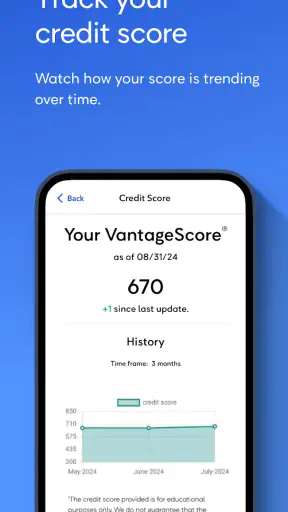
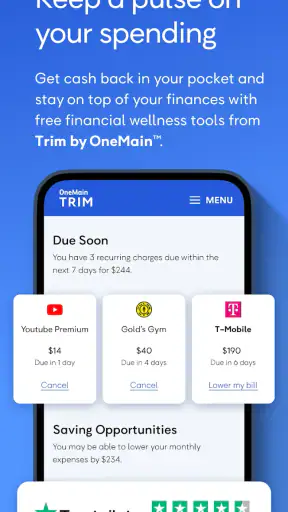
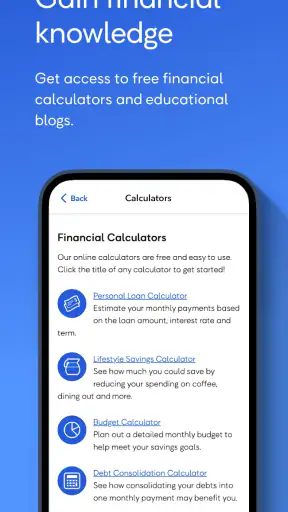
The app has been available since April 10, 2014, and its current version is 10.30.0. It supports Android 7.0 and later, which makes it usable on a wide range of Android devices, including older phones that cannot run many newer apps. That broad compatibility is practical, but it also means the visual experience may differ noticeably between an older handset and a current one. Keeping the operating system and app updated where possible is a reasonable step for stability and security.
Motor considerations during payment tasks
Payment work is where motor accessibility matters most. A user may need to tap small controls, enter numbers accurately, scroll through details, and avoid accidental confirmation. I recommend treating the process as a deliberate sequence rather than trying to complete it with one hand while walking or carrying something. A stable surface, a larger display, and a few uninterrupted minutes can make a meaningful difference.
For someone with tremors, limited dexterity, or difficulty with precise taps, the important test is not whether the home screen looks simple. It is whether the app provides enough visual separation and confirmation during the high-consequence steps. I would check whether the phone’s built-in accessibility settings make the controls easier to use, and I would avoid activating payment actions while the device is moving or the screen is crowded with notifications.
Users who rely on voice input may find that financial terminology needs careful checking. Dictation can mistake digits, names, or payment-related words, so I would review every field manually before submitting. Voice control can help reduce typing, but it should not replace visual verification for an irreversible or time-sensitive transaction.
A useful workflow for people with motor or memory challenges is to prepare before opening the app. Know which account or payment source you intend to use, keep the necessary information nearby, and write down the amount you expect to see. This is not a special feature of the app; it is a way of reducing cognitive and physical effort around a sensitive task.
Sensory and attention-friendly use
Financial stress can make even a short task feel difficult. I found that the app’s focused purpose is helpful in that situation because I am less likely to wander through unrelated features. Someone with attention difficulties may benefit from opening it only when there is a clear goal, such as checking the next payment or reviewing credit information, then closing it after recording the result.
For users sensitive to visual clutter, the best experience will depend on the phone’s display settings and the specific screen being used. I would enable the device settings that already work for you, such as larger text or a calmer display mode, and then check whether important labels remain fully visible. Enlarging text can sometimes cause wrapping or extra scrolling, so it is worth testing the payment path instead of assuming that one setting solves everything.
People with hearing loss are not dependent on audio for the basic concept of managing a loan, but any important status should still be confirmed visually. I would not rely on a sound or vibration alone to tell me that a payment succeeded. A written confirmation, account history, or other visible status is more dependable for a financial action.
Using OneMain Financial in real situations
A realistic payday check
Imagine I am paid on Friday and have a loan payment approaching. On Thursday evening, I open the app in a quiet room, check the amount and timing, and compare that information with my bank balance. If I decide to pay, I review the payment details slowly and keep the confirmation visible afterward. Later, I return to the account history rather than relying on memory.
This scenario shows where the app earns its place. It gives me a direct route to a OneMain loan without making me search through email, find a paper statement, or navigate a general banking site. The benefit is not dramatic automation; it is reducing uncertainty at the moment I need an answer.
For a person who shares financial responsibilities with a partner, the app can also support a clearer conversation, provided both people handle account information carefully. I would use it to verify the same figures before discussing a payment plan, rather than forwarding screenshots that expose more personal information than necessary. The narrower the information shared, the better.
When mobile access is especially useful
Mobile access matters when a borrower is away from a computer, has limited access to paper mail, or needs to check a loan during a change in routine. A phone can be easier to keep nearby than a laptop, and the app may feel less demanding than signing in through a browser each time. This is particularly useful for quick status checks, although I would still prefer a calm setting for entering payment details.
It can also help people who are uncomfortable with complicated financial websites. The dedicated app keeps the experience connected to OneMain rather than placing the user in a general-purpose portal filled with unrelated products. That reduced scope may support confidence for someone who wants only the loan information that matters today.
However, mobile convenience should not be confused with universal access. A person with an unreliable data connection, an older phone with limited storage, or a battery that frequently runs low may prefer a browser or another contact method as a backup. I would not wait until the payment deadline to discover that the app is difficult to use on a particular device.
How it compares with common alternatives
Compared with a general banking app, OneMain Financial is more specialized. A bank app usually wins for seeing income, everyday spending, transfers, and balances in one place. This app wins when the question is specifically about a OneMain loan or related credit information. I would choose the bank app for deciding whether I can afford a payment overall, then use this app to confirm the loan-side details.
Compared with using a mobile browser, the dedicated app can feel more direct because it is built around the same recurring tasks. A browser may be preferable on a shared device, on a phone where app installation is difficult, or for someone who wants to avoid adding another app. The choice is less about which method is universally superior and more about which route is easier to read and control on your device.
Compared with a budgeting app, this product is not trying to categorize every purchase or create a complete household plan. That is a meaningful trade-off. A budgeting tool can show whether a loan payment fits into the month; OneMain Financial is better suited to checking the loan relationship itself. Using both can make sense, but only if the extra information helps rather than creating another account to maintain.
Who should use it and who should skip it
I would recommend it to an existing OneMain borrower who wants a straightforward mobile way to review loan information, make payments, and keep an eye on credit-related details. It is also a reasonable option for someone who prefers a focused tool over a broad financial dashboard and wants access from an Android phone running version 7.0 or newer.
I would skip it if I do not have a OneMain loan or if my main goal is household budgeting across several institutions. It is also not the right primary tool for investment management, detailed expense analysis, or planning a complete debt strategy. In those cases, a bank app, budgeting service, spreadsheet, or conversation with a qualified financial professional may be more appropriate.
Families helping an older adult or someone with cognitive or motor limitations should test the app together before depending on it for deadline-sensitive payments. The person using it should be able to identify the correct account, read the amount, and recognize the final status. If that process is not comfortable, a supported workflow with another trusted method may be safer than assuming the app alone will solve the problem.
Remaining barriers and careful habits
The biggest barrier is the consequence of mistakes. A confusing entertainment app is annoying; a misunderstood payment screen can affect a person’s finances. I therefore judge this app by more than whether it opens quickly. It needs to support careful confirmation, clear reading, and a backup plan when the phone, connection, or user is having a bad day.
Another barrier is the boundary between loan management and broader financial understanding. Seeing a credit-related view can encourage useful monitoring, but it can also give a false sense that one screen explains a complicated credit history. I would treat the information as a prompt for questions, not as a complete financial diagnosis.
Privacy is another reason to be intentional. I would use a device lock, avoid signing in on public or borrowed phones, and be cautious about screenshots or notifications that reveal account details. These habits are particularly important for users who receive help from family members, caregivers, or support workers. Assistance should make the task easier without exposing more information than necessary.
One practical improvement is to create a personal checklist outside the app: confirm the account, check the amount, verify the date, submit only after reviewing, and save the confirmation in a secure place. This checklist helps users with memory difficulties and reduces the chance of rushing. It also makes it easier for a trusted helper to support the process without taking over every decision.
My inclusive verdict
OneMain Financial is a useful, focused finance app rather than an all-purpose money manager. Its free price and Everyone content rating make it easy to consider, while its 1M+ installs and 4.7 average from around 28 thousand ratings suggest that many borrowers find the mobile approach worthwhile. The developer, OneMain Financial, has kept the app centered on the company’s own loan and credit-related tasks instead of turning it into a crowded financial super-app.
I like it most for short, purposeful sessions: checking what is due, completing a payment carefully, or reviewing credit information before making a wider financial decision. Its strongest accessibility quality is this limited scope, which can reduce mental load. Its weakest point is that a simple-looking loan task still demands precision, and the experience may not suit every reader, motor need, device, or connection.
My recommendation is to test the complete payment journey before you depend on it. If the text is comfortable, the controls are manageable, and the confirmation is clear on your phone, it can be a practical part of your routine. If you need a full budget, broader account aggregation, or more tailored support for accessibility needs, pair it with a tool or assistance method that fills those gaps. Used with that realistic expectation, the app does what I would want from a dedicated loan companion: it makes a specific financial responsibility easier to check without pretending to replace everything else.
OneMain Financial FAQ
What is OneMain Financial, and what can I use the app for?
OneMain Financial is a mobile banking and lending app for existing and prospective customers in the United States. After signing in, users can typically review personal-loan details, check balances, view payment information, make one-time payments, manage scheduled payments, and update certain account information. The exact features available may depend on your loan, account status, location, and whether you are an existing customer.
Can I apply for a personal loan through the OneMain Financial app?
The app may allow eligible users to begin or continue a personal-loan application, but approval is not guaranteed. OneMain Financial generally evaluates information such as identity, income, expenses, credit history, and other application details. Loan amounts, interest rates, fees, repayment terms, and eligibility can vary significantly, so read the complete offer carefully before accepting it and confirm the total cost of borrowing.
Is the OneMain Financial app safe to use for managing my account?
The official OneMain Financial app is designed to provide secure access to your account using standard protections such as login credentials, encrypted connections, and device-based security options where supported. However, no online service is completely risk-free. Download the app only from an official app store, keep your operating system updated, avoid sharing verification codes, and contact OneMain Financial directly if you notice suspicious activity.
How can I make a payment with OneMain Financial, and are there fees?
Depending on your account and available app features, you may be able to make a one-time payment, schedule recurring payments, or manage an existing payment method. Processing times can differ, especially around weekends and holidays, so avoid waiting until the due date. Payment-related fees, returned-payment charges, and other costs depend on your agreement and payment method; review the terms before confirming a transaction.
What should I know before downloading and using OneMain Financial?
OneMain Financial is primarily useful for customers who already have, or are considering, a OneMain personal loan in the United States. It is not a general-purpose banking app and may offer limited value if you do not use the company’s financial products. You will need compatible Android or iOS software, an internet connection, and personal information for account access. Always verify the developer and privacy permissions before installing.












